
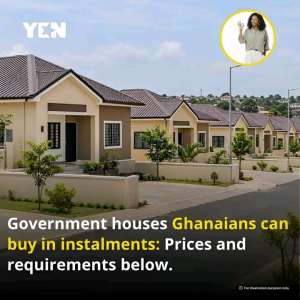
The State Housing Company Limited has opened sales for 195 homes at the Surge Homes development at Amrahia in the Greater Accra Region, offering prospective homeowners outright-payment, instalment and mortgage-financing options.
The development, located near the Adentan–Dodowa road, comprises detached two-, three- and four-bedroom houses. State Housing says the properties have spacious rooms, generous land sizes and litigation-free titles.
The two-bedroom house has a listed price of GH¢950,000, while the three-bedroom option costs GH¢1,295,000. The four-bedroom house is priced at GH¢2,170,000. A promotional discount of five per cent reduces the respective prices to GH¢902,500, GH¢1,230,250 and GH¢2,061,500. Prospective buyers should, however, confirm the validity period and conditions of the discount directly with the company.
Buyers who can afford the full price may make an outright payment. Those choosing the instalment arrangement may be required to pay a substantial initial deposit and complete the balance according to a schedule agreed with State Housing. The exact deposit, repayment period and handover conditions may vary and should be obtained in writing before any money is paid.
Mortgage financing is also available through financial institutions working with State Housing. Republic Bank signed a formal partnership with the company in December 2025 to provide tailored mortgage products, while Ecobank has announced a similar collaboration. The applicable interest rate, repayment period, deposit and maximum loan will depend on the lender’s assessment and the particular product selected.
This distinction is important because the National Homeownership Fund’s reported 8.4 per cent mortgage rate should not automatically be assumed to apply to every Surge Homes property. Although the Fund announced the return of a single-digit mortgage programme, individual banks may offer different rates. Republic Bank’s publicly available National Home-Ownership Mortgage Scheme page, for example, lists an 18.3 per cent annual rate and a maximum loan of GH¢350,000, showing why buyers must request a current, property-specific offer before making financial commitments.
Under the reported 8.4 per cent scheme, a person earning a net monthly income of GH¢2,500 could qualify for approximately GH¢143,000, with repayments of about GH¢1,231.95 a month over as long as 20 years. Someone seeking a GH¢500,000 loan would reportedly require a net monthly income of roughly GH¢8,700. Approval is not automatic and remains subject to income, age, credit history, existing debts and the lender’s affordability assessment.
The numbers reveal the central challenge. Even after the five per cent discount, a buyer paying half of the price of the least expensive house would need an initial amount of GH¢451,250 and would still owe another GH¢451,250. This means the homes are more likely to serve upper-middle-income households, established professionals, business owners and Ghanaians abroad than the average low-income worker.
State Housing has also encouraged pension contributors to explore whether their pension benefits can support the equity requirement for a mortgage. Buyers should not interpret this as permission to withdraw their SSNIT funds freely. Any pension-backed arrangement would be subject to Ghana’s pensions law, the rules of the relevant pension scheme, approval by the trustee and the mortgage lender’s requirements. Prospective applicants should obtain confirmation from their pension trustee and the National Pensions Regulatory Authority before relying on their retirement savings.
Applicants will generally need valid identification, proof of income or employment, photographs and evidence that they can provide the required deposit or qualify for a mortgage. Corporate bodies may also be considered where they can demonstrate verifiable income. Because some reports mention additional documentation and a non-refundable processing fee, applicants should confirm the official requirements and payment details directly with State Housing.
The announcement should therefore be understood correctly: these are houses being sold by a state-owned company, but that does not necessarily make them subsidised or affordable to every Ghanaian. Instalment payments can make the purchase process more flexible, but flexibility is not the same as affordability. A large deposit and expensive long-term financing may still place the properties beyond the reach of most workers.
Prospective buyers must also consider expenses beyond the advertised price, including mortgage interest, insurance, valuation, legal documentation, registration, maintenance and possible estate-management charges. The total amount paid over a 15- or 20-year mortgage could be considerably higher than the listed selling price.
For households unable to afford the Amrahia properties, attention is shifting to the revived Saglemi Affordable Housing Project. President John Dramani Mahama announced during an inspection on August 20, 2026, that the first 700 units were expected to be completed by March 2027. The remainder of the first 1,500-unit phase is scheduled for completion by December 2027.
Government has indicated that the Home Ownership Fund and participating financial institutions could help prospective Saglemi buyers meet a proposed 10 per cent deposit and provide low-interest, long-term financing. However, official house prices, detailed eligibility conditions and application dates had not been announced at the time of the statement.
Anyone interested in the Amrahia houses should deal only with State Housing and its officially named financial partners. Current prices, property availability, application fees, discount deadlines and bank terms should be verified through the company’s official website or offices before payment. Submitting an application or paying a processing fee does not by itself guarantee allocation of a house.

 ECOWAS, AfDB discuss ways to advance West Africa’s development priorities
 October 16: Cedi gains against dollar, sells at GHS12.25 on forex market, GHS11....
 “Our ancestors didn’t survive Notsie for us to divide ourselves” – Awadada
 Court jails mine worker 14 years for defiling 8-year-old girl at Manso Kumpese
 President Mahama orders review of Ghana’s disaster preparedness systems
 Galamsey: Ghana’s rivers now run chocolate and milk colour — Sam Jonah
 A nation of job-seekers will always be poor — Sir Sam Jonah
 CAGD pays promotion arrears to 56,003 GES teachers ahead of deadline
 “If you attack us with pepper spray, we’ll fight back” — NDC Yakubu Tony Aidoo w...
 We must support artisans to unlock job creation potential – Bawumia


