
The announcement by the National Tripartite Committee (NTC) that Ghana's National Daily Minimum Wage (NDMW) will increase to GH¢25.04 in 2027 and GH¢28.79 in 2028 should be welcomed. It is an important development in the country's efforts to improve the earnings and living conditions of workers. However, there is another group of people whose economic circumstances deserve equal, if not greater, attention: Ghana's pensioners. While government, employers and organized labour are negotiating improved remuneration for active workers, what deliberate arrangements are being made to protect those who have completed their working lives and depend almost entirely on monthly pension payments? Why should a worker who has retired after contributing to the development of this country be expected to survive on a pension substantially below the minimum wage established for someone who is still working? This is a question that government, the Social Security and National Insurance Trust (SSNIT) and the National Pensions Regulatory Authority (NPRA) must address.
The New Minimum Wage and the Pension Disparity
According to the NTC announcement of November 10, 2026, the national daily minimum wage will increase from GH¢21.77 in 2026 to GH¢25.04 effective January 1, 2027. It will rise further to GH¢28.79 from January 1, 2028. The new arrangement introduces a two-year minimum-wage negotiation framework intended to provide predictability, facilitate medium-term planning and budgeting, protect workers' incomes and sustain industrial harmony. The Committee has also indicated that it may review the rates if there are material changes in inflation, exchange rates and economic growth. These developments raise an important question: If the country can establish a minimum income below which employers should not remunerate workers, why can it not establish a corresponding minimum pension below which retired contributors should not be allowed to fall?
Let us consider the figures. Using 26 working days as an illustrative monthly conversion, the 2027 daily minimum wage of GH¢25.04 translates into approximately GH¢651.04 monthly. In 2028, GH¢28.79 translates into approximately GH¢748.54. These figures are calculations based on 26 working days, not monthly rates announced by the NTC.
Now consider the SSNIT minimum pension. For 2026, SSNIT announced a minimum monthly pension of GH¢400 for new pensioners. Existing pensioners who were receiving the previous minimum of GH¢300 were adjusted to GH¢409.56 through the indexation and redistribution arrangement. The disparity is glaring.
A new pensioner receiving GH¢400 monthly would earn approximately GH¢251 less than the illustrative 2027 minimum-wage equivalent of GH¢651.04. That is a difference of about 38.6%. Even the existing minimum pension of GH¢409.56 falls substantially below the projected 2027 minimum-wage equivalent. By 2028, the disparity will become even more pronounced if the pension floor remains unchanged. Should this situation be acceptable to a country that expects its retired workers to live with dignity?
Minimum Pension Must be brought at Par with Minimum Wage
I am proposing that government advises SSNIT and NPRA to work towards bringing the minimum monthly SSNIT pension at par with the national monthly minimum-wage equivalent. This should become an established national social protection policy rather than a matter left entirely to annual pension indexation negotiations. The argument is straightforward.
A minimum-wage policy recognizes that there is a basic income below which an active worker should not be expected to work. A minimum-pension policy should similarly recognize that there is a basic income below which a retired contributor should not be expected to survive. Retirement does not eliminate the need to eat, pay rent, purchase medication, pay utility bills, travel or meet family obligations. Indeed, the financial demands on some pensioners increase with age. Healthcare becomes more expensive, medical visits become more frequent, and the ability to undertake additional income-generating activities diminishes. A pensioner cannot simply walk into another workplace and negotiate a salary increase. The minimum pension must therefore reflect the realities of retirement, not merely the accounting considerations of pension administration.
Is SSNIT Doing Pensioners a Favour?
There is another matter I find necessary to address. At the January 8, 2026 media engagement to announce the pension indexation, SSNIT's Chief Actuary, Mrs. Evelyn Adjei, explained the redistribution mechanism and the adjustment of the minimum pension. She explained: "Redistribution is just a method where we take from those on the high pensions and bring it down and give it to those from the low pension." Her explanation raises an important issue about how SSNIT communicates pension adjustments to the public. The impression that could be created is that SSNIT is doing pensioners a favour by increasing the minimum pension from GH¢300 to GH¢400. With due respect, I do not subscribe to that interpretation.
SSNIT is not a charitable organization. It is not a philanthropic institution established to distribute gifts to elderly people. It is a statutory social security institution established to administer contributions and provide retirement benefits to eligible contributors. The pensioners are not beggars seeking assistance from SSNIT management. They are beneficiaries of a scheme into which they and their employers made contributions during their working lives. Indeed, contributors and pensioners are the very stakeholders whose interests SSNIT exists to serve. Although the Trust is not legally owned by contributors in the same way shareholders own a private company, contributors have a legitimate stake in its management, investment performance and accountability.
We must also remember that SSNIT does not depend exclusively on contributions to meet its obligations. It invests pension resources in various sectors of the economy to generate returns which support the payment of benefits. SSNIT's investment performance, therefore, is not a favour to pensioners. It is part of its responsibility to manage the funds entrusted to it.
The Trust's Director-General disclosed that SSNIT's assets under management had reached approximately GH¢25 billion in 2025. That is a substantial investment portfolio, and pensioners have every right to demand accountability regarding its performance.
- How much does SSNIT earn from its investments?
- What are its annual returns?
- How much is spent on administration?
- How much is reinvested?
- How much is available to support pension obligations?
These are legitimate questions. When management announces improvements in pension payments, it should communicate them as part of its statutory responsibilities rather than as though it were dispensing generosity.
There is also a distinction that should not be overlooked. The GH¢400 minimum applies to new retirees joining the scheme in 2026, while existing pensioners who were receiving GH¢300 were adjusted to GH¢409.56. These are different outcomes of the 2026 arrangement. SSNIT must communicate these distinctions clearly so that pensioners understand exactly what they are receiving and why.
Social Insurance: Some Pensioners Must Cushion Others
Perhaps the most important concept in this debate is the principle of social insurance.
A social insurance scheme is not simply an individual savings account in which each contributor receives precisely what he or she personally deposited, together with investment returns. It operates through collective contributions, risk-sharing and established benefit rules. People contribute according to their earnings and applicable contribution arrangements. Their eventual benefits depend on such factors as contribution history, pensionable earnings and the statutory formula. But social insurance also recognizes that those at the lower end require protection. This is why redistribution is important.
The 2026 indexation arrangement demonstrates that SSNIT already recognizes this principle. While the general indexation was 10%, comprising a fixed 6% increase and a redistributed component, pensioners at the lower end benefited from a substantially higher effective increase. That is social solidarity in practice.
Some pensioners receive relatively high monthly pensions because of their earnings and contribution histories. Others receive very modest pensions because their salaries and contributions were low. The question is whether the present redistribution mechanism is doing enough to protect the latter. I believe SSNIT and NPRA should examine whether a greater proportion of future indexation can be directed towards the lowest-paid pensioners. I am not advocating that everyone should receive identical pensions. People who contributed different amounts over different periods cannot automatically expect identical benefits. But neither should the contributory principle be interpreted so rigidly that a lowly paid worker who contributed for many years is condemned to poverty in retirement. Social insurance must mean something more than the mechanical payment of benefits according to contribution records. It must also embody solidarity and a reasonable level of social protection.
The Extraordinary Gap between the Highest and Lowest Pensioners
Let us examine another issue that should concern every stakeholder in Ghana's pension industry. The figures announced by SSNIT for 2026 reveal an extraordinary disparity between the highest and lowest monthly pensions. As of December 31, 2025, the highest-earning pensioner was receiving GH¢201,792.37 monthly. Following the 2026 indexation, that amount increased to GH¢213,991.47. At the other end, existing pensioners who were receiving the minimum of GH¢300 were adjusted to GH¢409.56.
Consider the implications of the ratio of highest to lowest monthly pension, using the published 2026 figures. Highest monthly pension = GH¢213,991.47, while Lowest existing monthly pension = GH¢409.56, unbelievably about 523:1. That is an extraordinary difference.
I appreciate that there are legitimate reasons for differences in pension entitlements. Some people contributed on substantially higher salaries, served longer periods and accumulated greater pension rights. We should not suggest that everyone must receive the same pension irrespective of their contribution histories. However, does the existence of different contribution histories mean that the gap cannot be narrowed at all?
Should someone who receives over GH¢200,000 monthly be considered in the same category of financial vulnerability as someone who receives GH¢409.56? The purpose of social insurance should not be merely to reproduce every income inequality that existed during active employment. It should also provide a reasonable measure of protection for those who are most vulnerable in retirement. SSNIT itself acknowledges this through its redistribution mechanism. The question is whether the existing redistribution is sufficiently ambitious.
There is also an important distinction in the figures. The highest pension quoted relates to the legacy pension arrangements, including PNDCL 247, while the newer Act 766 scheme has its own benefit calculations. These arrangements should not be confused when comparing individual entitlements. Nevertheless, the enormous disparity deserves public discussion.
Can the gap be narrowed a little more without undermining the legitimate entitlements of those who receive higher pensions? I believe this is a question SSNIT and NPRA should be prepared to answer. The objective should not be to punish high-earning pensioners. It should be to ensure that low-income pensioners are not abandoned.
What about the Lowly Paid Worker Who Contributed?
There is yet another question that deserves attention. In discussing social protection, we must distinguish between contributory pension benefits and non-contributory social assistance. Government operates social protection programmes for vulnerable people who may not have made the contributions required to qualify for a contributory pension. These programmes serve an important purpose. However, I find it difficult to accept that a worker who spent 15, 20 or more years in employment, made the required pension contributions and qualified for retirement benefits should be left with an amount that cannot meet basic monthly expenses.
If government recognizes the need to protect vulnerable people who have not accumulated sufficient pension contributions, why should it not also examine additional protection for low-income workers who contributed throughout their working lives? I am not suggesting that non-contributory social assistance beneficiaries and SSNIT pensioners must receive identical benefits. They belong to different policy arrangements. Nor am I suggesting that pension benefits should be distributed indiscriminately.
I am arguing that a qualifying worker who contributed, however modestly, should not be left below a reasonable minimum retirement-income threshold simply because his or her earnings during active employment were low. A worker should not be punished twice: first, by earning a low salary during active employment and, secondly, by receiving an inadequate pension after retirement. If a person worked hard, contributed according to the applicable rules and qualified for a pension, the scheme must provide meaningful protection.
Where the contribution-based calculation produces a pension below the proposed minimum social protection floor, SSNIT and government should explore an appropriate top-up mechanism. Such an arrangement could be supported by actuarially assessed redistribution within the scheme and, where necessary, a clearly funded government social protection commitment. The principle should be that no qualifying pensioner is abandoned to extreme financial hardship simply because his or her former salary was low.
Can the Pension Gap be narrowed without Destroying the Scheme?
This is a question that SSNIT and NPRA should be prepared to answer. The 2026 redistribution arrangement provides a useful starting point. SSNIT applies a fixed percentage increase and redistributes part of the overall indexation in favour of lower-income pensioners. But the authorities should consider whether a larger proportion of future indexation can be directed towards those receiving the lowest pensions. The difference between GH¢409.56 and GH¢213,991.47 should provoke a serious policy discussion.
The highest pensioner is entitled to the benefits earned under the applicable pension arrangements. However, the existence of a legitimate high entitlement should not prevent the authorities from examining ways of improving the circumstances of those at the bottom.
SSNIT should publish a comprehensive analysis showing:
- The number of pensioners receiving below GH¢500, GH¢1,000 and GH¢1,500 monthly.
- The number receiving GH¢5,000, GH¢10,000, GH¢20,000 and above.
- The distribution of pensions under PNDCL 247 and Act 766.
- The financial implications of progressively increasing the minimum pension.
- The extent to which investment income and redistribution can support improved benefits for low-income pensioners.
Such transparency would allow contributors and pensioners to understand the inequalities within the scheme and participate meaningfully in discussions about reform.
A 20–30% Increase in Existing Pensions is Urgently Necessary
Beyond establishing minimum-pension parity, I am also calling for an immediate adjustment of between 20% and 30% in existing monthly pensions. The economic circumstances confronting pensioners cannot be ignored. Food prices, transportation, electricity, water, rent, healthcare and other essential expenses continue to place considerable pressure on household incomes. Pensioners are particularly vulnerable because their incomes are generally fixed and their capacity to supplement them through employment is limited.
The annual indexation exercise, although necessary, must not become an excuse for postponing meaningful improvements in pension payments. Section 80 of the National Pensions Act, 2008 (Act 766), provides for the annual review of pension payments, indexed to wage inflation among active members or another rate determined by SSNIT in consultation with the NPRA. This provision gives the pension authorities an important responsibility to consider the economic circumstances of pensioners when determining annual adjustments.
I recognize that SSNIT must also protect the long-term sustainability of the pension scheme. However, sustainability must not be interpreted narrowly as the preservation of pension funds at the expense of the welfare of the very people for whom those funds exist. A pension scheme must be financially sustainable, but it must also deliver meaningful social protection. The proposed 20–30% increase should therefore be considered alongside the establishment of a new minimum-pension threshold. For example, a 20% increase on GH¢409.56 would produce GH¢491.47, while a 30% increase would produce approximately GH¢532.43. Even then, these amounts would remain below the illustrative 2027 minimum-wage equivalent of GH¢651.04. This demonstrates why an across-the-board percentage adjustment alone cannot resolve the problem. We need both a meaningful increase and a guaranteed minimum pension.
Government Must Provide Policy Direction
Government cannot simply leave the matter to SSNIT and NPRA as though pensioners' welfare were exclusively an administrative concern. Pension policy is an important component of national economic and social policy. The NTC has demonstrated that government, employers and organized labour can sit together, examine economic conditions and negotiate improved minimum earnings for workers. Why should a similar commitment not be demonstrated towards pensioners?
I am therefore calling on the Ministry of Finance, the Ministry of Labour, Jobs and Employment, SSNIT and NPRA to initiate discussions on a national minimum-pension policy. Government should advise the two pension institutions to examine the financial implications of bringing minimum pensions to the equivalent of the national monthly minimum wage and develop a practical implementation framework.
This should include:
- An immediate review of minimum pensions, with a target adjustment of between 20% and 30% for existing pensioners.
- A commitment to bring the minimum monthly pension to at least the equivalent of the national monthly minimum wage.
- A mechanism for automatically reviewing the minimum pension whenever the national minimum wage is adjusted.
- Special protection for pensioners receiving the lowest monthly payments through an appropriate redistribution mechanism.
- Greater transparency in the determination of annual pension indexation, including the assumptions about inflation, wage growth and fund sustainability.
- A published assessment of the pension gap and the options available to narrow it.
- A properly funded top-up arrangement for qualifying low-income pensioners whose contribution-based pensions fall below the established minimum social protection threshold.
- There must also be meaningful consultation with pensioner organizations.
Pensioners should not merely be recipients of decisions taken by others. They are stakeholders and contributors whose interests deserve representation.
The Question of Affordability and Sustainability
I anticipate that some officials may argue that a 20–30% pension increase and the proposed minimum-pension parity could impose considerable financial obligations on SSNIT. That argument deserves examination rather than outright dismissal. SSNIT has a statutory responsibility to ensure that the scheme remains sustainable for current and future pensioners. It must therefore undertake actuarial assessments before implementing significant changes. However, the financial implications must be properly established and presented to the public.
- How much would it cost to increase the pensions of those at the bottom of the payment scale?
- What would be the implications of raising the minimum pension to GH¢651 in 2027?
- What would be required to maintain parity when the minimum wage rises again in 2028?
These are questions that SSNIT and NPRA should answer transparently. The authorities should also examine the investment performance of pension funds, administrative expenditure, operational efficiency and opportunities to improve returns on investments. The objective should be to improve pensioners' welfare without compromising the ability of the scheme to meet its future obligations.
We should not forget that pension contributions are not gifts from government. They represent deferred earnings accumulated through years of work and contributions. Pensioners deserve accountability for how those contributions are managed.
Pensioners must not Become Second-Class Citizens
There is something fundamentally troubling about a society that celebrates workers' contributions during their productive years but becomes less concerned about their welfare after retirement. These are people who worked in our schools, hospitals, universities, public institutions, private companies, factories, farms and other establishments. They contributed to the development of Ghana and helped build the institutions that successive governments now administer. Many spent 30 or more years in active service, dutifully contributing to pension schemes in anticipation of a reasonable income in retirement. Their expectations should not be treated as unreasonable demands.
We must also remember that pensioners are consumers. They purchase food, pay utility bills, use transportation services and contribute to the local economy. Improving their incomes is not simply an act of compassion. It is also an economic intervention that can sustain household consumption and reduce financial dependence on working relatives. A pensioner who receives a reasonable monthly income is better positioned to meet personal needs without continually appealing to children, relatives and friends for assistance. That is what dignity in retirement should mean.
A Challenge to President Mahama and the Pension Authorities
President John Dramani Mahama has spoken about pension reforms and the possibility of a 13th-month pension payment. These proposals should be translated into concrete policies with clearly defined implementation timelines. However, the immediate question is how to improve the monthly pensions of those who are struggling today. A 13th-month payment, if implemented, would be welcome. But it cannot substitute for adequate monthly pension payments throughout the year.
The President should therefore direct the relevant ministries and pension authorities to examine the proposal for minimum-pension parity and the immediate 20–30% adjustment. The government should also encourage a national dialogue involving SSNIT, NPRA, organized labour, pensioner associations, civil society and independent pension experts. This should not be a political exercise. It should be a national conversation about social security, retirement dignity and the obligations of a society to those who have served it.
My Final Thoughts: The Time for Pension Justice is Now
The National Tripartite Committee has taken an important step by agreeing on minimum-wage rates for 2027 and 2028. But the announcement should also remind us that Ghana's pensioners deserve similar consideration. If the minimum wage is being raised to GH¢25.04 daily in 2027 and GH¢28.79 in 2028, the minimum pension should not remain disconnected from the economic realities reflected in those figures. I am not suggesting that pensioners and active workers perform identical economic functions. I am arguing that both deserve protection against incomes that cannot meet basic living expenses.
My proposal is simple: Government should advise SSNIT and NPRA to work towards establishing minimum-pension parity with the national minimum wage, while pursuing an immediate 20–30% adjustment in existing pensions. The authorities should undertake the necessary actuarial assessments, establish a realistic implementation timetable and communicate their decisions transparently.
But there is a bigger question that must not be ignored. What is the meaning of social insurance if a worker can contribute throughout a lifetime and still retire into poverty? What is the justification for a pension system that can pay one pensioner over GH¢200,000 monthly while another struggles to survive on approximately GH¢400?
Can we not narrow that gap through a more progressive redistribution policy without violating the legitimate entitlements of those who contributed more? And why should SSNIT's management communicate minimum-pension adjustments as though it were doing pensioners a favour? These are not unreasonable questions. They are questions of accountability, fairness and social justice. After all, retirement should be a period of rest, dignity and relative financial security, not a sentence to economic hardship.
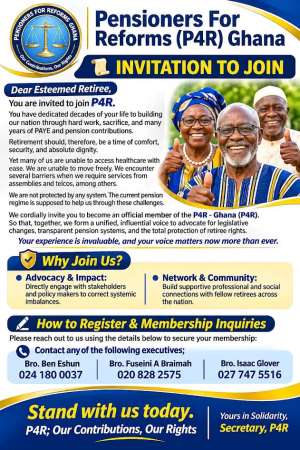
Our Contributions, Our Rights!
FUSEINI ABDULAI BRAIMAH
+233208282575 / +233550558008
[email protected]

 2027 Budget: ‘Another round of slogans with no jobs’ – Afenyo-Markin
 Women's Development Bank to begin operations in early 2027 – Ato Forson
 Govt to settle US$590m Eurobond and domestic bond obligations by December 31 – A...
 Govt allocates GH¢1bn to complete 35 Agenda 111 hospitals in 2027
 Ato Forson outlines eight pillars of government's US$10bn economic transformatio...
 Govt allocates GH¢600 million for construction of 10 regional stadia
 Government rules out new taxes in 2027, targets GH¢323.4bn revenue
 2027 Budget: Gov't to improve revenue collection without introducing new taxes –...
 New Economy to help Ghana process more of its resources locally – Ato Forson
 [Full text] Ato Forson presents 2027 budget in Parliament


