
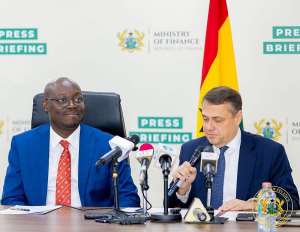
The International Monetary Fund (IMF) has reached a staff-level agreement with Ghana on the first review of the country's 36-month programme under the Policy Coordination Instrument (PCI), signalling continued progress in efforts to strengthen macroeconomic stability and sustain fiscal reforms.
The agreement follows discussions between an IMF team led by Ruben Atoyan and Ghanaian authorities during a mission to Accra from October 22 to November 4, 2026.
It is, however, subject to approval by IMF Management and the Fund's Executive Board before it can take effect.
In its end-of-mission statement, the IMF described Ghana's economic performance as resilient, pointing to strong growth, declining inflation and improvements in the country's fiscal position.
The Fund reported that real Gross Domestic Product (GDP) grew by 6.2 per cent year-on-year in the first half of 2026, while full-year growth is projected at 5.7 per cent.
Inflation also eased to 5.5 per cent in October, remaining below the Bank of Ghana's medium-term target range of 6 to 10 per cent.
On public finances, the IMF said the primary surplus was on course to meet the programme's end-year target, while Ghana's public debt had recorded a significant decline in recent years.
Foreign exchange reserves remain a major concern
Despite the positive economic indicators, the IMF identified mounting pressure on foreign exchange reserves as a key risk to the country's economic outlook.
It said the decline in reserves in recent months had led the authorities to introduce corrective measures, including transferring foreign exchange intermediation responsibilities from the Bank of Ghana to GoldBod and increasing gold sale requirements for large-scale mining companies.
The Fund stressed that the consistent implementation of these measures, alongside greater flexibility in the exchange rate, would be necessary to rebuild the country's reserves.
It also cautioned that Ghana remained vulnerable to fluctuations in global gold, cocoa and oil prices, geopolitical tensions and tighter international financial conditions.
Domestic vulnerabilities identified by the IMF include substantial domestic debt refinancing requirements, fiscal pressures from the energy, cocoa and gold sectors, as well as outstanding weaknesses in the financial sector.
2027 Budget targets 0.5% primary surplus
The IMF said the government's 2027 Budget is consistent with the objectives of the programme, with a commitment to achieving a primary surplus of 0.5 per cent of GDP on a commitment basis.
According to the Fund, the target builds on fiscal consolidation efforts undertaken in recent years and is expected to provide room for priority investments under the government's New Economy agenda, particularly in infrastructure and job creation.
However, it emphasised the importance of thorough project assessments, competitive procurement processes and strict expenditure controls to ensure value for money and safeguard debt sustainability.
The Fund also expects non-oil revenue to increase further in 2027, supported by tax measures approved in July 2026, changes to customs and excise legislation, and improvements in revenue administration.
Structural reform agenda records progress
On structural reforms, the IMF said implementation had been broadly satisfactory, highlighting the publication of the Fiscal Strategy Document, Parliament's approval of the new Cocoa Board Act and the continuation of quarterly electricity tariff adjustments.
It also noted that the authorities had completed a comprehensive review of customs and excise legislation ahead of schedule.
However, several reform commitments remain outstanding. These include improvements to the Bank of Ghana's liquidity management framework, the Integrated Tax Administration System, the operationalisation of the Fiscal Council and the preparation of the Fiscal Risk Statement.
The delayed publication of the audit of the Electricity Company of Ghana's (ECG) collection accounts was also identified as an outstanding commitment.
The IMF said maintaining the pace of reforms, rebuilding foreign exchange reserves and enforcing fiscal discipline would be critical to safeguarding Ghana's recent economic gains and laying the foundation for stronger, more inclusive and employment-driven growth.
 'There are no offices for Council of State members, you carry your office in you...
 Galamsey: 'Extremists can infiltrate northern Ghana' — UDS Professor warns
 IMF reaches staff-level agreement with Ghana on first review of 36-month program...
 Don’t treat Obuasi SHTS sexual abuse claims as business as usual—NAPO
 45 tonnes of cocaine were brought in by two Gulfstream jets in 2023 under Akufo-...
 22 drug seizures under Mahama means NACOC operations improved, intelligence now ...
 'NPP withdrawal of NACOC from port inspection teams in 2018 was major cause' – A...
 'NPP not morally qualified to lecture NDC on cocaine issues' — Akwatia MP hits b...
 Former Head of Civil Service explains why corruption is high in civil service
 SA evacuation: 'Some got GH¢2,000 instead of GH¢5,000; where is their money?' – ...


