
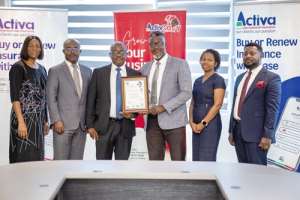
The Ghanaian insurance sector has witnessed remarkable growth and structural evolution in 2024. Leveraging National Insurance Commission (NIC) data, Accra Street Journal presents a comprehensive review of industry performance across profitability, asset accumulation, revenue, and claims, highlighting both life and non-life segments.
.
1. Industry-Wide Profit Trends (PAT 2020–2024)
The Ghanaian insurance industry has achieved strong bottom-line growth, with aggregate Profit After Tax (PAT) rising from GHS 293 million in 2020 to GHS 1.24 billion in 2024, representing a compound growth of 324% over five years.
Sector Contributions (2024)
- Life Insurance Sector: GHS 709 million (57% of total PAT)
- Non-Life Sector: GHS 532 million (43% of total PAT)
Key Insights:
- Life sector remains dominant but the gap with non-life insurers is narrowing.
- Non-life growth of 43% (GHS 317M → GHS 532M) shows stronger underwriting and investment efficiency.
- Life sector growth of 37% (GHS 512M → GHS 709M) reflects IFRS 17 implementation and improved Contractual Service Margin (CSM) reporting.
Top Profit After Tax Performers (2024):
Non-Life: Enterprise Insurance – GHS 17M | SIC Insurance – GHS 56M | Hollard – GHS 53M
Life: StarLife Assurance – GHS 310M | Enterprise Life – GHS 196M | Prudential Life – GHS 139M
.
2. Total Assets Rankings by Accra Street Journal (2024)
Asset concentration highlights market power and underwriting capacity.
Life Insurance Sector
- Top 5 life insurers control 77% of sector assets
- Top 10 account for 97% of total assets
Top 10 Life Insurers by Assets:
- StarLife Assurance – GHS 2.793B
- Enterprise Life Assurance – GHS 2.142B
- SIC Life – GHS 1.424B
- Prudential Life – GHS 986M
- Glico Life – GHS 653M
- Old Mutual Life – GHS 587M
- MiLife – GHS 550M
- Metropolitan Life – GHS 356M
- SanlamAllianz Life – GHS 277M
- Pinnacle Life – GHS 253M
Non-Life Insurance Sector
- Top 5 non-life insurers control 50% of sector assets
- Top 10 account for 73%
Top 10 Non-Life Insurers by Assets:
- Star Assurance – GHS 1.060M
- SIC Insurance – GHS 915M
- Enterprise Insurance – GHS 721M
- Ghana Union Assurance – GHS 651M
- Hollard Insurance Ghana – GHS 427M
- Vanguard Assurance – GHS 420M
- Glico General Insurance – GHS 399M
- SanlamAllianz – GHS 359M
- Activa International Insurance – GHS 303M
- Phoenix Insurance – GHS 211M
.
3. Revenue Performance Ranking by Accra Street Journal (2024)
Total industry revenue in 2024 reached GHS 7.34 billion, up 31% from GHS 5.32 billion in 2023.
- Non-Life Sector: GHS 5.01B (68% of total, 28% growth)
- Life Sector: GHS 2.33B (32% of total, 33% growth)
Top Revenue Generators:
Non-Life: Enterprise, SIC, Glico, Hollard, Star Assurance – generating 77% of sector revenue
Life: Enterprise Life, StarLife, Prudential, Salam Alliance, SIC Life – generating 97% of sector revenue
Insight: Life sector consolidation is high, but mid-tier players are expanding distribution channels.
.
4. Claims & Policyholder Benefits Ranking by Accra Street Journal (2024)
In 2024, total claims and benefits exceeded GHS 2.5 billion, reflecting operational credibility and public trust.
Non-Life Claims Paid
- Total: GHS 1.45B
- Top 5 contributors: Activa, Star Assurance, Enterprise, Hollard, Vanguard – 67% of total
Top 5 Non-Life Claims Payouts:
- Activa International Insurance – GHS 227M
- Star Assurance – GHS 217M
- Enterprise Insurance – GHS 201M
- Hollard – GHS 172M
- Vanguard – GHS 157M
Life Policyholder Benefits Paid
- Total: GHS 1.05B
- Top 3 contributors: StarLife, SIC Life, MiLife – 75% of total
Top 3 Life Benefits:
- StarLife Assurance – GHS 379M
- SIC Life – GHS 226M
- MiLife – GHS 174M
Insight: Concentrated payouts reflect mature product portfolios and strong claims-processing capacity.
.
5. Strategic Observations by Accra Street Journal
- Claims and PAT growth indicate increasing financial resilience.
- Asset concentration in life sector highlights market dominance but also systemic implications.
- Revenue growth across both sectors demonstrates sustained double-digit expansion.
- Market balance: Non-life shows competitive depth; life remains highly consolidated.
- Public trust depends on claims efficiency and payout reliability.
.


 24-hour economy market projects poorly planned, lacks consultation – Minority
 Stan Dogbe orders Greater Accra Regional Coordinating Council to restore Kpeshie...
 Police probe mysterious death of popular primary school teacher at Ampabame No. ...
 NACOC arrests three members of ‘Bolle Jos’ Network over French cocaine seizure
 Regular sex is not prostate cancer prevention — Urologist cautions
 Bawumia will use digitalisation to create opportunities for youth – Afenyo-Marki...
 NAPO calls for improved systems to address SHS placement concerns
 Bawumia listens to NASTAG concerns, outlines strategic agricultural transformati...
 Laboma Beach demolition leaves businesses counting losses
 Nigerian oil refinery Dangote launches IPO


