
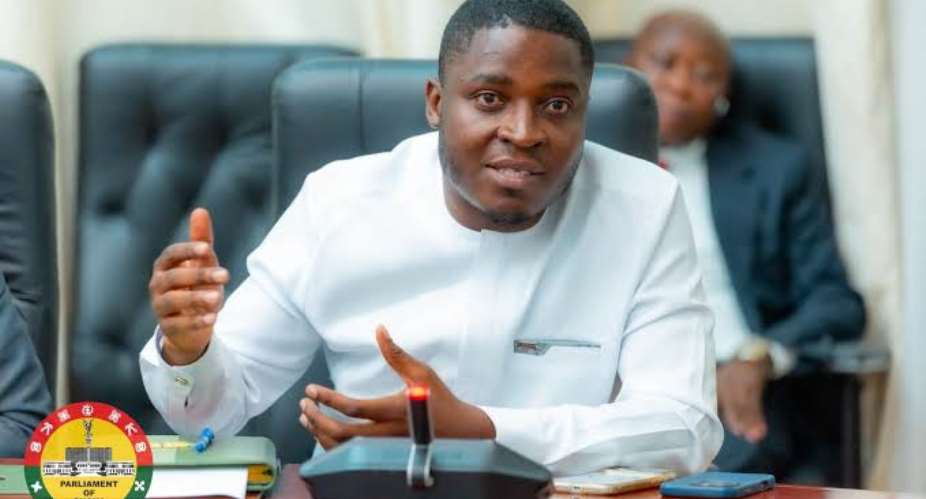
The Member of Parliament for Ketu North, Edem Agbana, has clarified the differences between the government's 24-hour economy policy and its newly introduced New Economy programme, describing them as separate initiatives with different funding arrangements and objectives.
He explained that while the 24-hour economy is driven by private sector investment, the New Economy agenda is a government-led programme involving a planned US$10 billion injection into the economy over the next four years.
Speaking on Channel One TV's The Big Issue on Saturday, November 14, Mr Agbana rejected suggestions that the introduction of the New Economy programme was an indication that the 24-hour economy policy had failed.
According to him, the 24-hour economy initiative is expected to attract approximately US$4 billion in private sector investment within four years, with businesses enrolled in the programme already taking steps to expand their operations.
“The 24-hour economy is essentially private sector-led. And as we speak, we have firms that are enrolled on the programme, and they are expanding,” he said.
He contrasted this with the New Economy agenda, which he said would be financed and driven by the government, with investments structured around eight key pillars.
“The New Economy is a wholly public sector, government-led US$10 billion injection into the economy on eight pillars,” he stated.
Mr Agbana maintained that the two policies were designed to complement each other rather than represent different versions of the same initiative.
The New Economy programme, unveiled by Finance Minister Dr Cassiel Ato Forson, is aimed at strengthening domestic production, encouraging local processing of raw materials, generating employment and reducing the country's reliance on imported goods.
Its first pillar focuses on consolidating Ghana's economic recovery through measures including maintaining inflation within single digits, keeping public debt at approximately 45% of Gross Domestic Product (GDP), sustaining a primary surplus of at least 0.5% of GDP and building stronger foreign exchange reserves.
 Another phone snatcher jailed 11 years in Ashaiman, marking second conviction in...
 Defeated NDC Central Regional Chairman blames former secretary, threatens legal ...
 Haruna Iddrisu urges AG, CID for prosecution of culpable persons in Obuasi SHTS ...
 24-hour economy is private sector-led, New Economy is US$10 billion government-l...
 Nana Kwasi breaks down in tears after reclaiming NDC Ashanti Regional chairmansh...
 Benjamin Danso unseats Ashie-Moore as NDC Greater Accra Regional Chairman
 Ghana to ratify three key AU financial institutions by 2027
 Catholic Bishops want full implementation of Kalba-Gbinyiri conflict report
 For Christ’s sake ‘cocaine economy’ label could damage Ghana’s reputation, put G...
 SpaceX's Starship set for return to Earth after failed booster catch


