
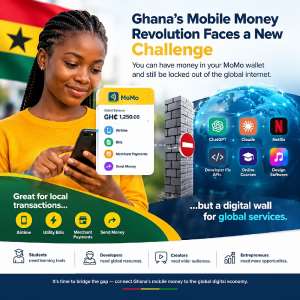
Ghana’s rapid adoption of mobile money has transformed how people send and receive funds, pay bills and conduct business. However, despite the widespread use of Mobile Money (MoMo), many users still face difficulties using their wallet balances to pay directly for international digital services, highlighting a significant gap between local financial inclusion and participation in the global digital economy.
For students, software developers, content creators, entrepreneurs and other digital professionals, accessing platforms such as ChatGPT, Claude and Netflix, as well as developer tools, online courses and design software, can involve additional steps. Users may need to transfer funds to a bank account, obtain an internationally accepted payment card or use another payment intermediary, potentially incurring extra fees and delays.
This challenge underscores an important limitation in Ghana’s digital financial ecosystem. Although mobile money has made domestic payments more accessible to millions of people, the ability to transact locally does not automatically guarantee seamless access to international online services. Differences in payment infrastructure, international card acceptance, foreign exchange arrangements and cross-border transaction requirements continue to create obstacles for some consumers.
The consequences extend beyond inconvenience. For students, restricted access to online learning resources can limit educational opportunities, while developers and entrepreneurs may struggle to obtain the digital tools and services needed to build products, improve productivity and compete internationally. Small businesses that depend on cloud computing, digital marketing and subscription-based software may also face additional administrative and financial costs.
Addressing this gap could create opportunities for fintech companies and developers to build payment solutions that connect Ghanaian mobile money wallets more directly with the international digital marketplace. Such services could simplify transactions, improve transparency in foreign exchange pricing, reduce unnecessary payment steps and make global digital products more accessible.
However, successful solutions must address regulatory compliance, consumer protection, fraud prevention, data security and the requirements governing cross-border payments. Clear pricing and reliable transaction processing will also be essential to building public trust.
As Ghana’s digital economy continues to expand, the next stage of financial inclusion must go beyond enabling people to transact within the country. It must also make it easier for individuals and businesses to participate in the global economy.
Bridging the gap between mobile money and international digital payments could unlock new opportunities for innovation, education, entrepreneurship and economic growth. The challenge now is to develop secure, affordable and convenient systems that allow Ghanaians to use their money more effectively in an increasingly connected world.

 Israel votes in first election since October 7 attack as Netanyahu faces crucial...
 US-EU trade truce at risk over $3.4 billion Airbus loan, Trump official warns
 Flavio Bolsonaro vows to lead opposition after Brazil court imposes travel ban
 Mecca pact nations hold talks with Iran to prevent renewed Middle East war
 New DStv sports package will save subscribers over Ghc500 monthly – Sam George
 Your past prescriptions never helped developing countries - TOR MD tells IMF
 Crude Distillation Unit turnaround was funded from TOR's internally generated fu...
 Trump offers $1 million for tipoffs leading to vote fraud conviction as midterms...
 UN cites 'ethnic cleansing' concerns around Israel's Palestinian displacement op...
 'Irresponsible media coverage is hurting Obuasi SHTS abuse probe' – Gender Minis...


