
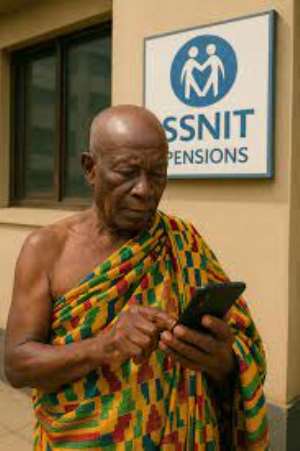
Ghana's pension debate is often reduced to one question: How much will pensions be increased next year? That question is important, but it is not the most important question. The bigger question is whether the architecture of Ghana's pension system is capable of delivering decent and sustainable retirement income to people who spend 20, 30, 35 or 40 years contributing to it. That question takes us directly to the National Pensions Act, 2008 (Act 766).
Act 766 was a major pension reform. It introduced Ghana's three-tier contributory pension system, established the National Pensions Regulatory Authority (NPRA), and placed the Basic National Social Security Scheme under the management of the Social Security and National Insurance Trust (SSNIT). The three tiers comprise the mandatory basic national social security scheme, a mandatory fully funded and privately managed occupational scheme, and voluntary fully funded provident and personal pension schemes. The law has since been amended, notably by Act 883 in 2014 and Act 1091 in 2023. The current consolidated version therefore differs in important respects from the original 2008 legislation. But Act 766 has now been operating for about 18 years. That is long enough to examine the evidence and ask a fundamental question: Does Ghana need another amendment to Act 766, or does it need a comprehensive review of the entire pension architecture? I believe the time has come for the latter. This is not a call to abolish Act 766. It is a call to learn from 18 years of experience and redesign those parts of the system that do not adequately protect contributors and pensioners.
The Three-Best-Years Formula
The first issue that deserves serious attention is Section 77. There is an important misconception that should be corrected at the outset. The original Act 766 provided that the minimum pension would be based on 50 per cent of the average annual salary for the three best years of a member's working life. But that provision was amended by Act 883 in 2014.
Under the current law, the minimum pension is based on 37.5% of the average annual salary for the three best years, while additional years beyond the minimum contribution period add 1.125% for each additional 12 months, up to a maximum pension rate of 60%. The question is not whether 37.5% sounds large or small. The question is whether the three-best-years method itself remains the fairest way of determining a worker's pension.
Imagine a worker who contributes to SSNIT for 30 or 35 years. During those years, the worker may experience promotions, stagnant salaries, inflation, transfers, periods of unemployment, economic crises and changes in occupation. Yet, when retirement comes, the pension calculation places particular emphasis on three years.
There is logic behind using the best years. It protects a worker whose earnings increased substantially towards the end of the career. But there is also a weakness. The method does not necessarily provide a transparent relationship between a worker's entire contribution history and the pension ultimately received.
A comprehensive review should therefore examine whether Ghana should move towards an indexed career-average earnings system. Under such a system, earnings throughout the worker's career could be revalued to reflect changes in wages or prices before calculating the pension. The debate should therefore not be reduced to: "Should Ghana retain three years or use 30 years?" The real question is: Which formula produces the fairest, most transparent and financially sustainable relationship between contributions and retirement benefits? That is a question for actuaries, economists, labour representatives, employers, pensioners, SSNIT, NPRA and Parliament.
A Pension is not Charity
This distinction is important because pensioners are sometimes spoken about as though government is doing them a favour by increasing pensions. It is not charity. Workers contribute. Employers contribute. The money is invested. The system accumulates assets. Benefits are subsequently paid. The entire architecture is based on a social-security contract. Act 766 itself states that the objective of the scheme is to provide pension benefits to ensure retirement-income security and ensure that workers receive retirement and related benefits when due.
The pensioner therefore has a legitimate right to ask whether the system is producing an adequate retirement income.
What Happens to Investment Returns?
This brings us to investment. SSNIT is not simply keeping workers' money in a vault.
It invests pension funds. The results can be substantial. The Bank of Ghana's 2025 Financial Stability Review reports that the Basic National Social Security Scheme's assets under management rose from GH¢22.35 billion in 2024 to GH¢29.07 billion in 2025. It also reports a nominal investment return of 23.8 per cent in 2025 and a real return of 8.0 per cent, after negative real returns in 2022, 2023 and 2024. These figures deserve closer public attention.
If pension assets generate investment income,
- What portion is required to maintain the long-term actuarial health of the scheme?
- What portion is needed to meet current pension obligations?
- What portion is reinvested?
- What portion is consumed by administration and investment costs?
- And, when there is a sustainable surplus, should pensioners receive some additional benefit from the performance of the assets accumulated with their contributions?
I am not proposing that SSNIT simply declare a commercial dividend every year. That would be irresponsible. A social-security scheme must maintain sufficient reserves to meet future liabilities.
But Ghana should consider a statutory mechanism under which sustainable investment surpluses can, subject to actuarial certification, be used to improve pension benefits. This could take the form of a pension enhancement reserve, a bonus pension, a special indexation adjustment or another mechanism determined by law.
The principle is simple: When the pension fund performs exceptionally well, the pensioner should not be invisible in the distribution of the benefit.
Transparency Should Precede any Dividend
Before discussing an annual pension "dividend", however, Ghana needs far greater transparency.
Every year, contributors and pensioners should be able to see, in simple language:
- Total contributions received;
- Benefits paid;
- Investment income;
- Realized investment gains;
- Unrealized gains and losses;
- Administrative expenses;
- Investment-management fees;
- Asset allocation;
- Investment performance against appropriate benchmarks;
- Actuarial liabilities;
- Actuarial reserves; and
- The amount available for any sustainable benefit enhancement.
That information should not be buried in a lengthy annual report. It should be presented in a simple Pensioner's Annual Financial Statement. People should be able to understand what happened to their money.
Government must not Profit from Delayed Pension Payments
Another important issue is delayed remittances. Act 766 imposes obligations on employers and provides penalties for failure to pay contributions. Act 883 also amended the enforcement provisions relating to unpaid contributions. The principle is sound.
If an employer deducts pension contributions from a worker's salary, that money belongs to the pension system. Government should be held to the same principle. Where government obligations to SSNIT are delayed, the delay should carry a clearly defined financial consequence. This is not an argument against government. It is an argument for consistency. A private employer cannot be expected to pay penalties for delayed pension contributions while the State operates under a different economic logic. There should be a statutory interest mechanism. A more technically defensible formula could combine inflation, prevailing Treasury-bill rates and, where appropriate, exchange-rate movements. The objective should be to ensure that SSNIT does not suffer a financial loss because an employer, including government, failed to remit money on time. Nobody should make a financial gain by withholding pension money.
Government Arrears: a Changing Picture
It is also important to acknowledge the evidence that the situation is not static. In March 2026, SSNIT's Director-General said government had been consistently honouring its monthly contribution obligations. By August 2026, the Ghana News Agency reported that government had cleared 2025 SSNIT contribution arrears. The same report said SSNIT's assets under management had risen substantially and that more than GH¢3.83 billion had been paid in benefits during the first half of 2026.
This is important because pension advocacy should distinguish between historical arrears, cleared arrears and current obligations. The reform question remains valid even when arrears are cleared: What legal mechanism prevents the recurrence of the problem and compensates the pension fund for the financial cost of any future delay? That is the issue Parliament should address.
Tier Two: the Other Pension Question
If Tier One is important, Tier Two deserves equally serious attention. Tier Two is a mandatory, fully funded, privately managed occupational pension scheme under Act 766. This is workers' retirement money. The scale is enormous. The Bank of Ghana's 2025 Financial Stability Review reports that private pension assets were heavily invested in Government of Ghana securities, although the proportion fell from 72.9% in 2024 to 64.5% in 2025. Ordinary shares increased from 5.7% to 12.2% over the same period. This demonstrates both the scale and the concentration of pension investment.
Government securities may be regarded as relatively important instruments for pension portfolios, but concentration also creates risk. If a large proportion of pension assets is exposed to one sovereign borrower, the pension system becomes connected to the financial condition of the State. Ghana should therefore continuously ask: Who carries the investment risk? The pensioner should not carry every risk
A pension fund manager can make an investment decision. A trustee can approve an investment policy. A custodian can hold the assets. A regulator can supervise. The pensioner ultimately wants one thing: a secure retirement benefit.
If an investment loses value because of normal market fluctuations, that is part of investment. But where a loss results from negligence, fraud, breach of fiduciary duty, conflict of interest or violation of investment rules, the consequences should not simply be transferred to the pensioner. The law already recognizes fiduciary duties and provides a regulatory framework.
NPRA's mandate includes approving, regulating and monitoring trustees, pension fund managers and custodians. It also has powers to investigate complaints and impose administrative sanctions or fines. NPRA maintains lists of registered pension fund managers, custodians and corporate trustees. So the issue is not whether regulation exists. The issue is whether regulation is strong enough, enforcement is sufficiently visible and accountability is sufficiently effective.
Fund Managers must Face Meaningful Accountability
Every pension fund manager should be subject to continuous scrutiny of:
- Investment performance;
- Risk management;
- Management fees;
- Related-party transactions;
- Conflicts of interest;
- Concentration of investments;
- Corporate governance;
- Compliance history;
- Liquidity;
- Investment decisions;
- The qualifications and conduct of key investment personnel; and,
- The public should also know when a pension fund manager has been sanctioned and what corrective action was taken.
There is no reason to hide regulatory enforcement from the people whose retirement money is being managed. The names of registered providers are already published by NPRA. The next step should be greater public transparency about compliance and performance.
Pension Management is not a Game of Heads-I-Win, Tails-You-Lose
This is the principle that should govern Tier Two. If the investment performs well, everybody should benefit appropriately. If the market performs badly despite prudent management, the loss may be an unavoidable investment risk. But if the loss results from misconduct or negligence, there must be consequences.
The system cannot become one in which the pensioner bears the economic consequences while the service provider continues collecting fees. The law should therefore examine whether existing liability and compensation mechanisms are sufficiently strong.
Pensioners Need a Stronger Voice
There is another weakness that deserves attention: representation. Section 35 of Act 766 provides for the SSNIT Board and includes one representative of the National Pensioners Association. The current provision also includes representatives of organized labour, employers, government ministries and the Director-General of SSNIT. The NPRA Board likewise includes representatives from relevant public institutions, organized labour, employers and the National Pensioners Association.
The question is whether one pensioner representative is enough. Ghana now has a growing number of pensioners and several pensioner organizations. The answer should not be to declare that one organization automatically speaks for everyone. Nor should it be to allow every group to demand a seat without an orderly mechanism. The solution is a transparent representation system.
Parliament should consider whether the law should provide for more than one pensioner representative, selected through a transparent and accountable process that recognizes the diversity of pensioner organizations. Pensioners should not be represented merely because they are beneficiaries. They should be represented because they are stakeholders in the governance of the system.
Should Pensioners Chair SSNIT and NPRA?
This proposal also deserves discussion. The chairperson of SSNIT or NPRA should not be selected simply because he or she is a pensioner. The essential qualifications should include independence, competence, integrity, governance experience and a deep understanding of pensions. A retired actuary could qualify. A retired banker could qualify. A retired accountant could qualify. A retired labour leader could qualify. A retired pension administrator could qualify. A retired academic with appropriate expertise could qualify.
If that person is also a pensioner, there is nothing wrong with that. The principle should be: Pension institutions should be governed by people who understand the consequences of pension decisions. He who feels it, knows it. It should not be a situation where the suggestion is that we give the rioters cake, since the price of bread has been increased. There are many managers who are insensitive to human suffering, unfortunately. There are many who have no idea about what suffering is. If they knew, the minimum pension will be Ghc600 per month or ghc20 a day and not ghc400!
The Law Should Protect Pensioners from Conflicts of Interest
One of the most important concepts in pension governance is fiduciary duty. People managing pension assets are not dealing with ordinary commercial money. They are dealing with money entrusted to them for a specific purpose. The law should therefore require strong disclosure of conflicts of interest.
A trustee, director, fund manager or other decision-maker should not be able to participate in an investment decision from which that person or a related party may benefit without full disclosure and appropriate safeguards. This is especially important as pension assets become larger.
GH¢111 Billion Demands Extraordinary Vigilance
The scale of Ghana's pension industry demonstrates why reform cannot wait until there is a crisis. According to the NPRA's 2025 figures reported publicly, total pension assets under management increased from about GH¢86.09 billion in 2024 to approximately GH¢111.1 billion in 2025. SSNIT had 261,928 pensioners and 2.14 million active contributors at the end of 2025. These are enormous sums. They belong, directly or indirectly, to workers and pensioners. As the assets grow, governance must become stronger, not weaker.
We should not Confuse Asset Growth with Pension Adequacy
This is another distinction that deserves attention. A pension fund can have billions of cedis in assets while individual pensioners remain financially vulnerable. Asset growth is important. Investment returns are important. Actuarial sustainability is important. But the ultimate purpose of the pension system is not to accumulate the largest possible asset balance. It is to provide retirement security.
The 2025 experience illustrates the point. SSNIT's investment performance improved significantly, with the Bank of Ghana reporting a real return of 8.0% in 2025 after negative real returns in earlier years. That is encouraging. But pension adequacy must still be examined separately.
The question is not simply: How much money does SSNIT have? It is: What does that money mean for the person receiving GH¢400, GH¢600, GH¢1,000 or GH¢2,000 a month?
The Pensioner's Purchasing Power Matters
A nominal pension increase does not automatically mean an improvement in living standards. If food, transport, electricity, water, rent and medicine rise faster than the pension, the pensioner can receive a larger number of cedis and still become poorer in real terms. This is why Section 80 of Act 766 is so important. It requires SSNIT to review pension payments annually and index them to wage inflation of active members or another rate determined by the Trust in consultation with the NPRA Board.
But Ghana should now ask whether annual indexation alone is sufficient protection against extraordinary inflationary episodes. A serious review could examine whether the law should permit a supplementary mid-year adjustment when inflation or essential household costs move beyond a specified threshold. That would not mean automatic increases every few months. It would mean having a transparent emergency mechanism.
Act 766 should Introduce Stronger Automatic Stabilizers
The pension system should not depend excessively on political discretion. The greater the discretion, the greater the temptation to portray ordinary statutory obligations as political generosity. Instead, Ghana should establish clearer statutory rules. For example: If inflation rises beyond a defined threshold, there should be an actuarial review. If investment returns substantially exceed the long-term actuarial assumption, a portion could be considered for benefit enhancement. If government delays pension remittances, statutory interest should apply. If a fund manager breaches fiduciary duties, penalties and compensation should follow. If pension assets become excessively concentrated in one asset class, the regulator should intervene. If pension adequacy falls below an objectively determined threshold, Parliament should be required to consider remedial measures. These mechanisms would reduce uncertainty.
A Comprehensive Review should Ask 15 Questions
The review of Act 766 should therefore consider at least the following:
1. Is the three-best-years formula still the fairest basis for calculating pensions?
2. Should Ghana consider an indexed career-average earnings formula?
3. Is the current 37.5% minimum pension rate adequate in relation to contributions?
4. Should there be a sustainable mechanism for sharing exceptional investment surpluses with pensioners?
5. Should annual pension indexation be supplemented by an emergency mid-year adjustment mechanism?
6. Should delayed government pension contributions attract statutory interest?
7. Should that interest reflect inflation, Treasury-bill rates and, where necessary, exchange-rate depreciation?
8. Are Tier-Two trustees, custodians and fund managers sufficiently accountable when investment decisions go wrong?
9. Are sanctions sufficiently strong when losses result from negligence or misconduct?
10. Should pension fund fees and management costs be more transparent?
11. Is the current degree of pension-fund exposure to government securities appropriate?
12. Should pensioners have greater representation on the SSNIT and NPRA boards?
13. Should representation recognize more than one pensioner organization through a transparent selection mechanism?
14. Should retired professionals with pension-sector experience have a formal advisory role?
15. Should Act 766 require an independent actuarial and governance review of the entire pension system at regular intervals?
These are not unreasonable questions. They are the questions one would expect from a country serious about retirement security.
Parliament should Commission an Independent Pension Review
Rather than asking SSNIT or NPRA to defend the existing system, Parliament should commission an independent national pension review. The review should include actuaries, economists, investment specialists, labour representatives, employers, pensioners, legal experts, civil-society organizations and representatives of the informal sector. It should examine the entire chain: contribution → investment → administration → investment return → pension calculation → indexation → pension adequacy. It should also examine the three tiers together. The review should publish its methodology, assumptions and findings. Most importantly, the review should not begin with the conclusion that Act 766 is either good or bad. It should begin with evidence.
Do We Need Another Pension Reform?
The answer is probably yes. But reform should not mean changing one percentage here and another percentage there. Ghana needs a second-generation pension reform. The first generation created the three-tier architecture. The second generation should make the architecture more transparent, accountable, sustainable and pensioner-centered.
Act 766 was enacted in 2008. The Ghana of 2026 is not the Ghana of 2008. The investment market is different. The pension assets are vastly larger. The economy has experienced extraordinary inflation and debt restructuring. The demographics are changing. Technology has transformed financial administration. The number of pensioners has increased. And Ghana now has nearly two decades of practical experience with the system. That experience should be used.
Pensioners Are Not Asking for Favours
There is a moral dimension to this debate that should never be forgotten. The pensioner was once a young worker. He or she worked when the body was strong. The pensioner paid taxes. The pensioner contributed to SSNIT. The pensioner's labour built schools, hospitals, roads, businesses, universities and public institutions. Some pensioners worked for decades before receiving their first pension cheque. They are not asking government to give them somebody else's money. They are asking whether the pension system is delivering what the social contract promised. That is a legitimate question.
My Thoughts: The Ultimate Test
Ghana should therefore stop measuring pension reform only by the size of an annual percentage increase. We should measure it by the dignity it provides to the person who has finished working. The real test is not how large SSNIT's assets are. It is not how impressive an institution's headquarters may be. It is not how many investment deals have been concluded. It is not even how many billions of cedis are under management. The ultimate test is much simpler: Can a Ghanaian who has worked and contributed for decades retire without being condemned to financial insecurity?
If the answer is not a convincing yes, then pension reform remains unfinished business. Act 766 should therefore be reopened, not to destroy the three-tier system, but to improve it. The three-best-years formula should be examined. Investment governance should be examined. Tier Two should be examined. Government remittance obligations should be examined. Fund-manager accountability should be examined. Pensioner representation should be examined. The relationship between investment returns and pension benefits should be examined. And above all, the purchasing power and dignity of the pensioner should become the central measure of success.
Ghana has had 18 years to learn what works and what does not. The time has come to use those lessons to build a pension system in which the worker does not merely contribute to retirement security, but can actually see and feel that security when retirement arrives.
FUSEINI ABDULAI BRAIMAH
+233208282575 / +233550558008
[email protected]

 Israel votes in first election since October 7 attack as Netanyahu faces crucial...
 US-EU trade truce at risk over $3.4 billion Airbus loan, Trump official warns
 Flavio Bolsonaro vows to lead opposition after Brazil court imposes travel ban
 Mecca pact nations hold talks with Iran to prevent renewed Middle East war
 New DStv sports package will save subscribers over Ghc500 monthly – Sam George
 Your past prescriptions never helped developing countries - TOR MD tells IMF
 Crude Distillation Unit turnaround was funded from TOR's internally generated fu...
 Trump offers $1 million for tipoffs leading to vote fraud conviction as midterms...
 UN cites 'ethnic cleansing' concerns around Israel's Palestinian displacement op...
 'Irresponsible media coverage is hurting Obuasi SHTS abuse probe' – Gender Minis...


