
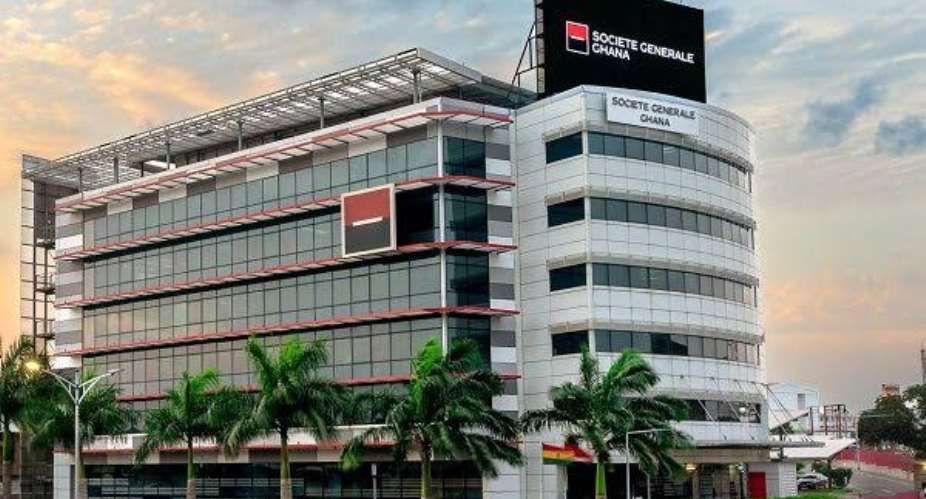
When the Social Security and National Insurance Trust (SSNIT) announced that it had increased its stake in Société Générale Ghana from 19.36% to 24.36%, the announcement was presented as an important investment development. SSNIT acquired an additional 5% stake following Société Générale Group's exit from Ghana. Attijariwafa Bank acquired the majority 55.22%, while SSNIT increased its existing holding. SSNIT says the transaction strengthens its investment portfolio on behalf of Ghanaian workers and pensioners and will help safeguard and grow contributors' retirement assets. That is an important objective. But there is another side to the story. What does this investment actually mean for the ordinary pensioner? That is the question SSNIT should now answer. Not in general terms. Not merely by saying that the investment will create "long-term value". Pensioners deserve to know how the investment process eventually translates into stronger pension benefits. This is particularly important because the institution at the center of this transaction has a remarkable history with SSNIT and Ghanaian workers.
From SSNIT's bank to Société Générale
The story goes back almost half a century. In February 1975, Security Guarantee Trust Limited was incorporated as a private limited liability company. According to Société Générale Ghana's own historical account, the institution was wholly owned by SSNIT. In February 1976, SSNIT changed its name to Social Security Bank Limited. The Bank of Ghana granted it a banking license in September 1976, and the bank officially opened its doors to the public in January 1977. The historical significance should not be lost.
The World Bank recorded that the Social Security Bank, established in 1977, was wholly owned by SSNIT and that its original objective was to provide banking services to workers. In other words, the institution that eventually became Société Générale Ghana has a direct historical connection with Ghana's social-security system. It was not simply another commercial bank that happened to emerge in Ghana. It began as a bank wholly owned by SSNIT. Over the years, however, its ownership changed. In 1995, SSNIT made a public offer and divested part of its shareholding. In 1997, strategic investors acquired a controlling interest. Société Générale subsequently acquired a controlling stake, and the bank became SG-SSB in 2004 and Société Générale Ghana in 2013. And now, almost five decades after the birth of Social Security Bank, SSNIT has increased its ownership in the institution once again. There is therefore a fascinating historical circle.
A bank created under the ownership of the social-security institution for the benefit of workers has evolved into a major commercial bank in which SSNIT is again increasing its stake. That history makes the present investment deserving of more than a passing news report.
The Question SSNIT Must Answer
SSNIT says the increased shareholding will strengthen its investment portfolio and help safeguard and grow contributors' retirement assets. Fine. But pensioners should ask: How? How does a 24.36% ownership of Société Générale Ghana translate into better retirement security for the pensioner? How much did SSNIT pay for the additional 5%? What was the valuation of the bank at the time of the transaction? What return does SSNIT expect from the investment? What dividend income does SSNIT expect to receive? What has Société Générale Ghana historically paid in dividends to its shareholders? What are the projected dividends over the next five and ten years? And if the value of the shares increases, how does that increase ultimately benefit the pension scheme?
These are not hostile questions. They are questions that should be asked whenever an institution manages the retirement savings of hundreds of thousands of people.
Follow the Money
There is an even bigger question. SSNIT invests pension contributions in shares, government securities and other assets because contributions alone are not the whole story. Investment income is an important component of the financial sustainability of a pension scheme. SSNIT itself has said that the increased Société Générale holding is intended to safeguard and grow contributors' retirement assets. Therefore, pensioners should be able to follow the money. If SSNIT invests GH¢1 billion and eventually receives GH¢100 million in dividends and capital gains, where does that money go? Does it increase the reserves of the pension scheme? Does it reduce pressure on contributions? Does it improve the capacity of SSNIT to pay pensions? Does it influence annual pension indexation? If so, by how much? And if investment income does not directly determine annual pension increases, what is the precise mechanism by which investment returns contribute to pension sustainability? These questions should not be considered unreasonable. They go to the heart of accountability in pension management.
The Pensioner's Reality
The investment discussion can easily become too technical. Shareholding. Portfolio diversification. Capital appreciation. Dividend yield. Risk-adjusted return. Corporate governance. All of these are important. But behind every SSNIT investment is a human being. There is the pensioner who receives a modest monthly pension and has to pay for food, electricity, water, transportation, rent, medical expenses and other necessities. There is the pensioner who spent decades contributing to the system and now depends almost entirely on the monthly pension.
For such a pensioner, the question is not whether SSNIT owns 19.36% or 24.36% of a bank. The question is: What difference does that ownership make to my pension? That is the question that should never be lost in the language of investment. Is the investment income reaching the pensioner?
SSNIT has demonstrated that it can produce investment returns. Its 2026 indexation announcement, for example, says the 2026 pension adjustment was structured around a 10% overall indexation, combining a fixed 6% increase with redistribution of the remaining 4% to support lower-paid pensioners. This raises an important issue. If SSNIT's investments generate substantial income, pensioners need greater clarity about the relationship between: contributions → investments → investment returns → pension fund resources → pension payments. Where exactly does the investment return enter the chain? And how much of the pension being paid today is supported by investment income generated from the contributions of yesterday's workers? This information would help pensioners understand the economics of the scheme instead of simply hearing that SSNIT's assets are growing.
Asset Growth is not the same as Pension Adequacy
This distinction is crucial. A pension fund can have a growing investment portfolio while individual pensioners continue to experience financial hardship. The two things are not necessarily contradictory. A pension fund has long-term obligations. It must preserve capital, generate returns, meet current pension payments and prepare for future beneficiaries. But the existence of those long-term obligations should not prevent pensioners from asking how investment performance is reflected in pension adequacy. Indeed, SSNIT's own explanation of pension calculation makes clear that pensions depend on factors including the member's age, average salary over the three best years and contribution history. Investment performance operates within this broader structure. The pensioner therefore deserves to understand not just how much SSNIT has invested, but how investment performance affects the sustainability and adequacy of the pension system.
What was the Original Purpose of the Investment?
The history of SSB makes this question even more interesting. When Social Security Bank was established, it was wholly owned by SSNIT and had an original objective of providing banking services to workers. Today, the successor institution is no longer a SSNIT-owned workers' bank. It is a commercial bank with a multinational history, a new majority shareholder and SSNIT as a significant minority shareholder.
That transformation is not necessarily a problem. Banks evolve. Ownership changes. Governments privatize enterprises. Strategic investors enter and exit markets. But when SSNIT once again increases its ownership, pensioners are entitled to ask what lessons have been learned over the nearly five decades since Social Security Bank was established.
- What has SSNIT earned from its historic investment?
- What did the divestment of shares achieve?
- What dividends and capital gains did SSNIT receive over the years?
- What was the value of the holding before the latest transaction?
- And why is increasing the stake now considered an attractive long-term investment?
These are questions about the history and economics of pension investment, not politics.
The Hard Questions
Perhaps SSNIT should publish a simple pensioner-friendly statement answering the following:
- How much did SSNIT pay for the additional 5% in Société Générale Ghana?
- What is the current total value of SSNIT's 24.36% holding?
- What dividends has SSNIT received from Société Générale Ghana over the past five years?
- What dividend income does SSNIT expect from the enlarged holding?
- What return on investment does SSNIT consider satisfactory for this investment?
- What are the principal risks associated with the investment?
- How does this investment compare with alternative investments that SSNIT could have made with the same money?
- How much of SSNIT's annual pension expenditure is financed by investment income?
- What proportion of SSNIT's total investment income ultimately supports pension payments?
- If investment returns increase significantly, does that create additional room for improving pension benefits? If not, why not?
- How does SSNIT measure whether an investment has actually improved the financial position of the pension scheme?
- Will SSNIT publish the performance of this investment annually so that contributors and pensioners can see whether it is meeting its objectives?
These are reasonable questions for an institution managing workers' retirement security.
The 265,000+ Pensioners
There is another dimension that cannot be ignored. SSNIT is not investing on behalf of a handful of wealthy shareholders. It is investing on behalf of workers whose contributions finance a national social-security system and pensioners who depend on that system. For the pensioner receiving a modest monthly income, a statement that an investment will "create long-term value" is not enough. The pensioner wants to know: How much value? By when? Measured against what benchmark? And how does that value affect my retirement security? These questions become even more important when SSNIT itself describes the investment as being undertaken on behalf of Ghanaian workers and pensioners and says it is intended to contribute to improved retirement benefits. The burden should therefore not be on pensioners to understand complicated investment terminology. SSNIT should explain it in language the pensioner can understand. This is not an argument against investment
There is an important distinction here. Pensioners are not saying SSNIT should keep pension contributions under a mattress. Nor are they saying that SSNIT should not invest in banks, equities or other productive assets. Quite the contrary. A pension fund that does not invest its assets prudently risks losing purchasing power and weakening its ability to meet future obligations. The issue is value for money, transparency, accountability and the ultimate beneficiary of investment performance. When SSNIT says an investment is good for pensioners, pensioners should be entitled to ask SSNIT to demonstrate the benefit. That is not hostility. That is accountability.
My Thoughts
The story of Social Security Bank is therefore more than a story about a bank. It is part of the history of Ghana's social-security system. An institution wholly owned by SSNIT was established in the 1970s, with an original objective of serving workers. It eventually became a publicly listed bank, attracted strategic investors, came under Société Générale control and ultimately became Société Générale Ghana. Now SSNIT is increasing its stake again. The transaction gives us an opportunity to ask a larger question: After nearly 50 years of pension investment, how effectively are the returns from SSNIT's investments being converted into retirement security for Ghanaian workers and pensioners? That is the conversation that should follow the announcement. Not simply: "SSNIT has bought another 5%." But: "What will this 5% earn, who will benefit, and how will the pensioner know?" The ordinary pensioner should not have to be an investment analyst to understand what is happening to his or her retirement money. SSNIT owes contributors and pensioners a clear explanation.
FUSEINI ABDULAI BRAIMAH
+233208282575 / +233550558008
[email protected]

 SkyTrain trial: High Court adjourns case management conference to October 19
 Edudzi Tameklo recalls how Duffuor was slapped with GH¢100 million bail in 2020,...
 About 800 Director I and II applicants unreachable due to invalid contact number...
 'Boakye Agyarko was seen as anti-Bawumia' – Lecturer on John Boadu’s victory
 'NPP delegates made wrong choice electing John Boadu as chairman' — Political Sc...
 MTN Ghana secures new 5G spectrum in 700 MHz and 3 GHz bands
 Bawumia explains NPP hunt for winnable parliamentary candidates, not deep-pocket...
 Ghana to tap Egypt’s expertise for new capital city, housing projects – Mahama
 Ghana, Egypt deepen cooperation in health, defence and housing
 NDC Women’s Organiser Abigail Mensah condemns alleged pepper spray plot by Hawa ...


