
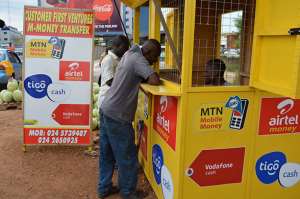
When President John Dramani Mahama took office on January 7, 2025, his administration inherited a public debate shaped by a clear political promise: the abolition of the Electronic Transfer Levy (E-Levy). Parliament subsequently repealed the E-Levy in 2025. Yet in May 2026, a new controversy emerged over a proposed 0.75% charge on transfers from mobile-money wallets to bank accounts.
The charge was proposed not as a new tax enacted by Parliament, but by Mobile Money Fintech Limited (MMFL), the operator of MTN Mobile Money, and was scheduled to take effect on June 1, 2026. The May 2026 proposal carried a cap of GH¢5 per transaction. The Bank of Ghana subsequently directed MMFL to pause implementation on May 26 pending further consultation.
That GH¢5 figure must not be confused with an earlier regulatory development. In January 2024, under the previous administration and the then Bank of Ghana leadership, the Bank reportedly gave a “no objection” to a 0.75% wallet-to-bank charge with a GH¢55 cap. The January 2024 and May 2026 figures therefore relate to different stages and proposals.
The controversy is consequently larger than the amount involved. It raises questions about regulatory consistency, consumer protection, transparency and the constitutional boundary between a legitimate private transaction fee and a compulsory charge that may, in substance, resemble taxation.
From e-levy to abolition
The E-Levy became one of Ghana’s most politically contentious taxes after its introduction in 2022. The NDC, then in opposition, strongly criticised the measure, while public opposition helped make it a major political issue. The charge was subsequently repealed after the change of government.
That history matters because the political argument surrounding the present controversy is not simply about 0.75%. It is about whether a government that promised relief from E-Levy-related charges can preside over the emergence of another transaction charge that ordinary users may experience in a similar way.
However, the comparison must be made carefully. The proposed MMFL charge was not itself an Act of Parliament imposing a tax. It was a proposed fee within the mobile financial-services ecosystem. The more defensible question is therefore whether a privately imposed regulatory or transaction fee can, depending on its legal character and operation, raise constitutional concerns where it begins to resemble a compulsory public levy.
That distinction is essential. Political criticism is strongest when it rests on facts rather than on simply calling every transaction charge a “tax.”
The new charge and the facts
The May 2026 proposal came from Mobile Money Fintech Limited (MMFL), the operator of MTN Mobile Money. MMFL notified customers that a 0.75% fee, capped at GH¢5, would apply to direct wallet-to-bank transfers from June 1, 2026.
The proposal was not ultimately implemented on that date. On May 26, the Bank of Ghana directed MMFL to pause implementation pending further consultation, citing the need to ensure that changes to charges in the mobile financial-services ecosystem were introduced fairly and in a manner that protected consumers.
This point is important because the charge should not be described as though it is currently being collected. As of the Bank of Ghana’s May 26, 2026 directive, implementation had been suspended.
There is also an important historical distinction. In January 2024, the Bank of Ghana, under the previous administration and the then Governor, Dr Ernest Addison, had reportedly issued a “no objection” concerning a 0.75% wallet-to-bank charge with a GH¢55 cap. The later GH¢5 cap in May 2026 was therefore not the same figure as the GH¢55 cap associated with the January 2024 regulatory position.
Same economic concern, different legal character
For an ordinary user, the practical concern is straightforward: a charge attached to moving money from a mobile-money wallet to a bank account increases the cost of conducting a transaction.
Consider a GH¢1,000 wallet-to-bank transfer. At 0.75%, the charge would amount to GH¢7.50, but because the proposed May 2026 arrangement was capped at GH¢5, the applicable charge would have been GH¢5.
That is materially different from the old E-Levy. Under the former E-Levy regime, the legal basis, collection mechanism and statutory framework were different. The proposed MMFL fee should therefore not simply be labelled a “rebranded E-Levy” as a statement of legal fact.
But the political comparison remains understandable. Both involve charges associated with electronic financial transactions, and both affect the cost of moving money through Ghana’s increasingly digital economy.
The real issue is therefore not whether the two charges are legally identical. They are not. The question is whether citizens should be concerned when transaction costs that affect everyday financial activity are introduced through regulatory or commercial mechanisms without the same level of parliamentary scrutiny associated with taxation.
The bank of Ghana's role
The January 2024 “no objection” was issued under the previous Bank of Ghana leadership and during the previous NPP administration. The May 2026 suspension, by contrast, was directed under the current Bank of Ghana leadership.
It would therefore be inaccurate to suggest that the current Bank of Ghana leadership approved the original 2024 arrangement. Equally, it would be too simplistic to treat the 2024 regulatory decision as irrelevant merely because political and institutional leadership subsequently changed.
The Bank of Ghana is a continuing public institution. Its regulatory history therefore matters across administrations.
The stronger institutional question is whether the regulatory framework sufficiently protects consumers and ensures that charges imposed within the financial system remain within their proper legal character. If a charge is genuinely a commercial or regulatory fee, it should be capable of being justified on that basis. If, however, a charge effectively operates as a compulsory public levy, the constitutional implications become more serious.
Article 174(1) of the 1992 Constitution provides that taxation is not to be imposed otherwise than by or under the authority of an Act of Parliament. That provision does not mean that every private transaction fee is a tax. It does mean that the legal character of a compulsory charge cannot be determined merely by the label attached to it.
The Bank of Ghana’s May 2026 intervention was therefore significant. It showed that regulatory oversight can respond when a proposed charge raises concerns about fairness, consultation and consumer welfare.
Ghana’s experience with taxes and levies provides a useful backdrop
Fuel users, for example, encounter multiple statutory charges embedded in petroleum pricing. The energy-sector framework has included the Energy Sector Shortfall and Debt Repayment Levy and the Road Fund Levy, among others. Recent legislative changes have also altered some of those rates.
The popular description of the GH¢1 “Dumsor Levy” formally the Energy Sector Recovery Levy illustrates how quickly a statutory charge can become part of the everyday cost of living.
The lesson is not that every levy is illegitimate. Governments need revenue, and Parliament has constitutional authority to legislate taxation and public charges. The lesson is that transparency about the legal basis, purpose, rate and ultimate incidence of every charge matters.
Consumers should know what they are paying, why they are paying it, who authorized it and how the money is ultimately used.
The political cost of broken expectations
The NDC’s historical opposition to the E-Levy makes the politics of the present controversy unavoidable.
But the strongest criticism should not rest on slogans about hypocrisy. It should rest on the principle of consistency.
A political movement that successfully campaigns against a transaction charge creates expectations about how it will approach similar burdens when it assumes office. Where a new charge emerges, even through a different legal mechanism, the government must explain the distinction convincingly.
That is particularly important in an economy where citizens already encounter multiple taxes, levies, fees and regulatory charges.
The credibility of government depends not merely on whether it technically complied with the law, but also on whether citizens understand the reasons for the charges imposed upon them.
The us$214 million question
The wider debate about public charges has also unfolded against concerns about the cost of economic programmes. The International Monetary Fund reported approximately US$214 million in quasi-fiscal losses associated with the artisan and small-scale gold component of Ghana’s Gold-for-Reserves programme through the third quarter of 2025.
That figure, however, should not be presented simplistically as an “alleged loss” of the current government or as a straightforward operational loss by GoldBod. The IMF’s treatment concerns costs and losses associated with the programme, while Ghanaian authorities have emphasized the foreign-exchange and macroeconomic benefits of the programme.
The broader lesson is nevertheless relevant: when government-linked financial arrangements create costs, citizens deserve transparency about how those costs arise, who bears them and what public benefit is expected in return.
Governance and legal concerns
The central legal question is therefore not simply: “Is this another E-Levy?”
The more precise question is:
What is the legal character of the charge, who authorised it, what regulatory framework governs it, and what safeguards protect the consumer?
That formulation is stronger because it avoids prejudging the legal answer.
A private company may have legitimate reasons to revise its charges. Regulators may also have legitimate authority to approve, review or restrict charges within the financial system. But the exercise of regulatory authority must remain transparent, lawful and consistent with consumer protection.
Where a charge is sufficiently similar in substance to a tax or compulsory public levy, constitutional questions inevitably arise. Those questions should be resolved through law and transparent regulatory reasoning rather than partisan rhetoric.
What the suspension should teach us
The May 26 suspension should therefore be viewed not merely as a political victory for one party or a setback for another.
It should be treated as an opportunity to improve Ghana’s regulatory architecture.
Before any significant new charge is introduced into the mobile financial-services ecosystem, consumers should receive adequate notice. The basis for the charge should be publicly explained. The responsible institution should identify the legal authority for the charge. Stakeholders should have an opportunity to comment where the proposed change is substantial. And the regulator should publish the principles used to determine whether the charge is fair and proportionate.
These safeguards would benefit both consumers and legitimate financial-service providers.
The trust deficit toward 2028
The NDC built considerable political capital by promising to remove the E-Levy and reduce burdens on ordinary Ghanaians. The subsequent repeal of the E-Levy fulfilled an important part of that commitment. But political promises are tested not only by formal repeal. They are also tested by what happens afterward.
The government therefore has an opportunity to demonstrate that the post-E-Levy era will not simply replace one controversial transaction charge with another mechanism that citizens perceive as equivalent.
The NPP, for its part, has a legitimate role in scrutinizing the proposal and demanding accountability. But that scrutiny will be most credible when it distinguishes clearly between a tax enacted by Parliament and a private fee proposed within a regulated financial system.
The issue should be bigger than partisan advantage.
It should be about whether Ghana can build a financial system in which innovation, commercial freedom, regulatory oversight and consumer protection coexist without leaving citizens uncertain about the charges imposed on their everyday transactions.
The 0.75% MMFL proposal has exposed a broader problem in Ghana’s public-policy debate: the gap between the legal description of a charge and how ordinary citizens experience it.
The january 2024 bank of ghana “no objection” And the may 2026 proposal must be distinguished. The earlier regulatory position involved a 0.75% charge capped at gh¢55, while the may 2026 mmfl proposal involved a 0.75% charge capped at gh¢5. The latter was subsequently suspended by the bank of ghana pending consultation.
Those facts matter.
So does the distinction between a private transaction fee and a tax. Ghana should not casually collapse the two. At the same time, neither should the State assume that changing the label of a charge eliminates legitimate constitutional, regulatory or public-interest questions.
The way forward is therefore neither partisan denial nor political exaggeration. It is transparency, lawful authorisation, meaningful consultation, consumer protection and consistent regulatory standards.
If Ghana is serious about restoring public confidence in its institutions, citizens should never have to guess whether the charge appearing on their transaction receipt is a commercial fee, a regulatory charge or, in substance, something closer to a tax.
That clarity is not a political luxury. It is a requirement of good governance.
By Ing. Prof. Zakaria Issaka and Abubakari Najimu Kaleem
 Israel must win 'because we’ve got no other choice’, PM Netanyahu tells UN
 Mahama reiterates Ghana's commitment to two-state solution to Palestine-Israel c...
 Ablakwa calls for Return of African Artefacts held abroad
 Madina MP Francis-Xavier Sosu reportedly collapses while speaking at GIMPA
 Kumasi drivers, passengers react to 8% transport fare increase
 I will unite Africa, Caribbean and Latin America into world's biggest trading bl...
 Mahama petitioned to halt Sentuo Airport Garden City construction after sod cutt...
 Government should not fund the $4 billion Accra-Kumasi Expressway project — Alan
 Democracy must deliver tangible social benefits to citizens – Mahama
 Court to rule on bail applications of six accused in 3.9-tonne cocaine seized in...


